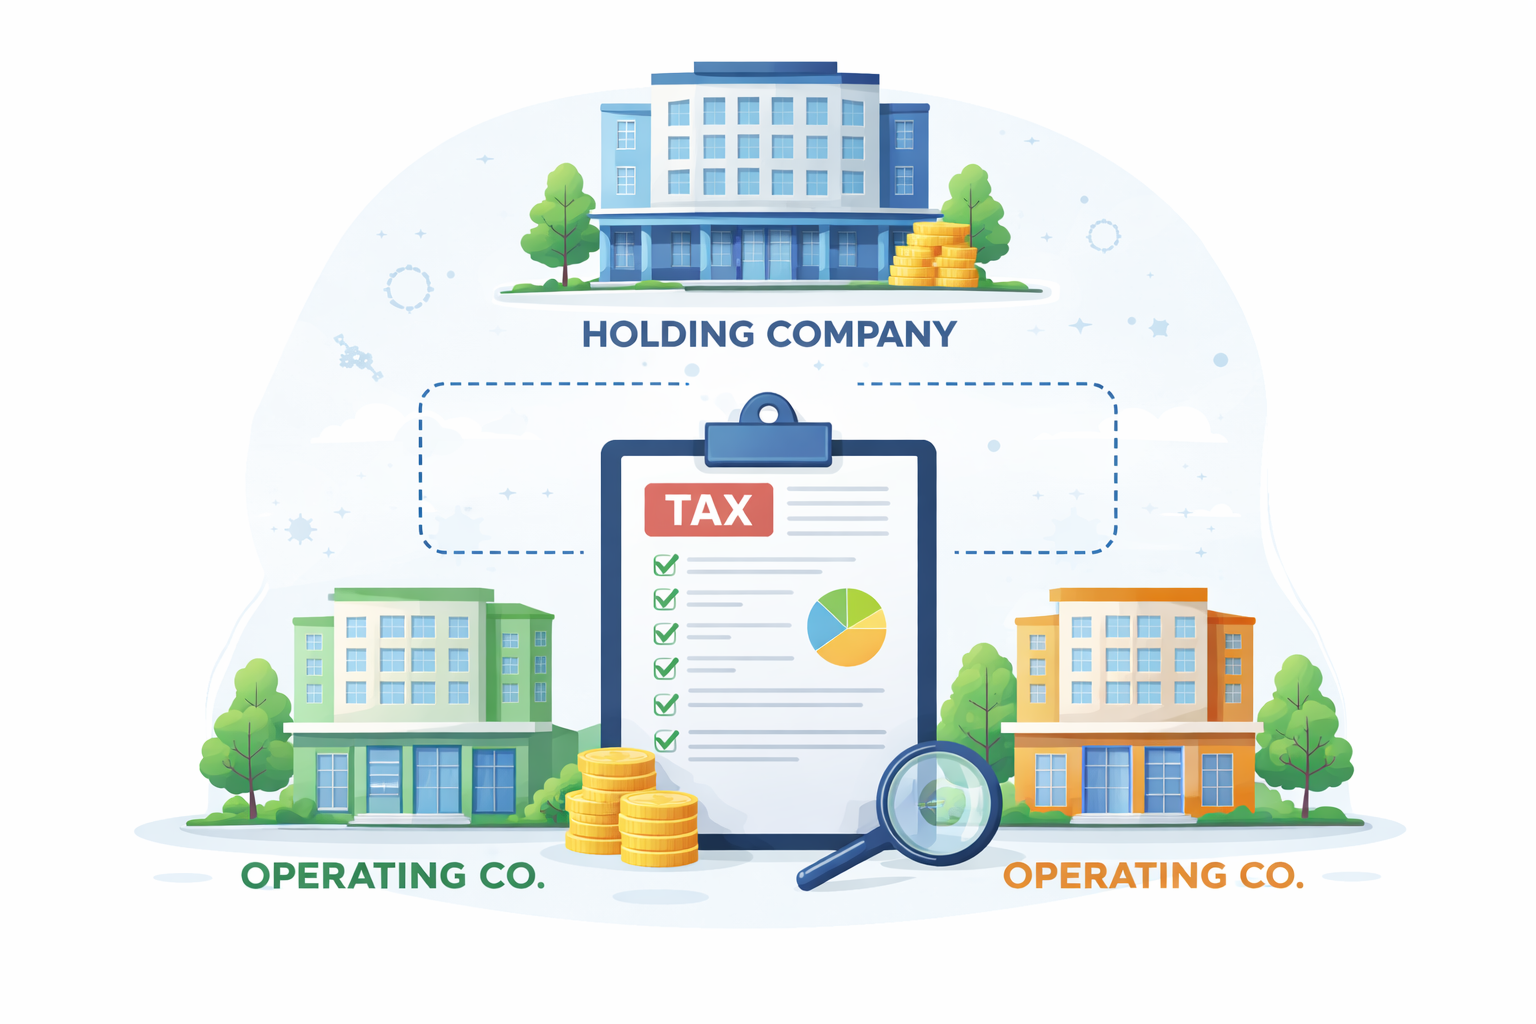
Holding and Operating Company in Switzerland: Building a Strong Corporate Structure
Switzerland offers an attractive environment for entrepreneurs seeking stability, credibility, and tax efficiency. One of the most strategic corporate models is the separation of a holding company and an operating company.
This structure is widely used by business owners who want to optimize taxation, protect assets, and prepare their company for future growth or exit. Proper planning from the beginning ensures long-term advantages and compliance with Swiss regulations.
The Operating Company: Managing Daily Business
The operating company is the active business entity. It:
- Provides services or sells products
- Employs staff
- Enters into contracts
- Generates operational revenue
- Assumes commercial risks
Since it interacts directly with clients and suppliers, the operating company carries most of the legal and financial exposure.
The Holding Company: Ownership and Strategic Control
A holding company is a separate legal entity that owns shares in the operating company. It does not engage in day-to-day commercial activities.
Instead, it may:
- Hold shares in subsidiaries
- Own intellectual property
- Manage group investments
- Provide internal financing
By separating ownership from operations, the business clearly divides risk from asset control.
Tax Advantages of a Swiss Holding Structure
Participation Deduction on Dividends
Swiss tax law offers participation deduction mechanisms at federal and cantonal levels. If conditions are met:
- Dividends paid from the operating company to the holding company are largely tax-privileged.
- Capital gains from selling subsidiary shares may benefit from reduced taxation.
This allows profits to circulate within the group with minimal tax impact.
Flexibility for Future Sale
If the holding company sells the operating subsidiary:
- Gains may qualify for participation deduction.
- Sale proceeds remain within the corporate structure.
- Personal income tax can be deferred until distribution to shareholders.
This creates flexibility for reinvestment or structured wealth planning.
Strategic Profit Distribution
Without a holding structure, dividends are taxed directly at shareholder level.
With a holding entity:
- Profits are first distributed to the holding company.
- Earnings can be reinvested.
- Shareholders decide when to trigger personal taxation.
This provides better control over timing and liquidity.
Structuring Your Company in Baar, Switzerland
The Canton of Zug, including Baar, is internationally known for its business-friendly environment and competitive tax framework.
During your company foundation in Switzerland, implementing a holding structure from the outset ensures an efficient setup.
A professional domicile address in Switzerland strengthens credibility and compliance. Depending on your structure, appointing a titular managing director may also be required under Swiss law.
Ongoing accounting and financial reporting ensures transparency and compliance with Swiss corporate regulations.
Is a Holding–Operating Structure Right for You?
This model is particularly suitable if:
- Your company generates consistent profits
- You plan to reinvest earnings
- You own intellectual property or valuable assets
- You anticipate expansion or a future exit
Each business situation should be carefully assessed to ensure the structure aligns with Swiss tax and corporate law requirements.
📞 Contact DeinDomizil
📞 +41 (0)41 410 61 61
🏢 Blegistrasse 7, 6340 Baar, Switzerland
If you are considering structuring a holding and operating company in Switzerland, our team in Baar will support you with professional domicile, foundation, and compliance services tailored to your needs.